May 2016 Article Archives - Page 3
FASB ISSUES Accounting Standards Update 2026-01 EQUITY (Topic 505) – Initial Measurement of Paid-in-Kind Dividends on Equity-Classified as Preferred Stock - April 2026 Summary
Summary Why Is the FASB Issuing This Accounting Standards Update? The Board is issuing this Update to provide authoritative guidance on how an issuer should initially measure paid-in-kind (PIK) dividends on equity-classified preferred stock. The amendments do not affect an entity’s determination of when to recognize PIK dividends. Stakeholders expressed concerns that current generally accepted accounting principles (GAAP) do not address ...
Read More
Final Regulations Under Section 4501 – Changes of Potential Interest to Cooperatives
Congress added Section 4501 to the Code as part of the Inflation Reduction Act of 2022, P.L. 117-58 (August 16, 2022). This section imposes a 1% excise tax on certain repurchases of corporate stock. Section 4501(b) limits applicability to corporations which are “covered corporations,” defined as “any domestic corporation the stock of which is traded on an established securities market (within the meaning of section ...
Read More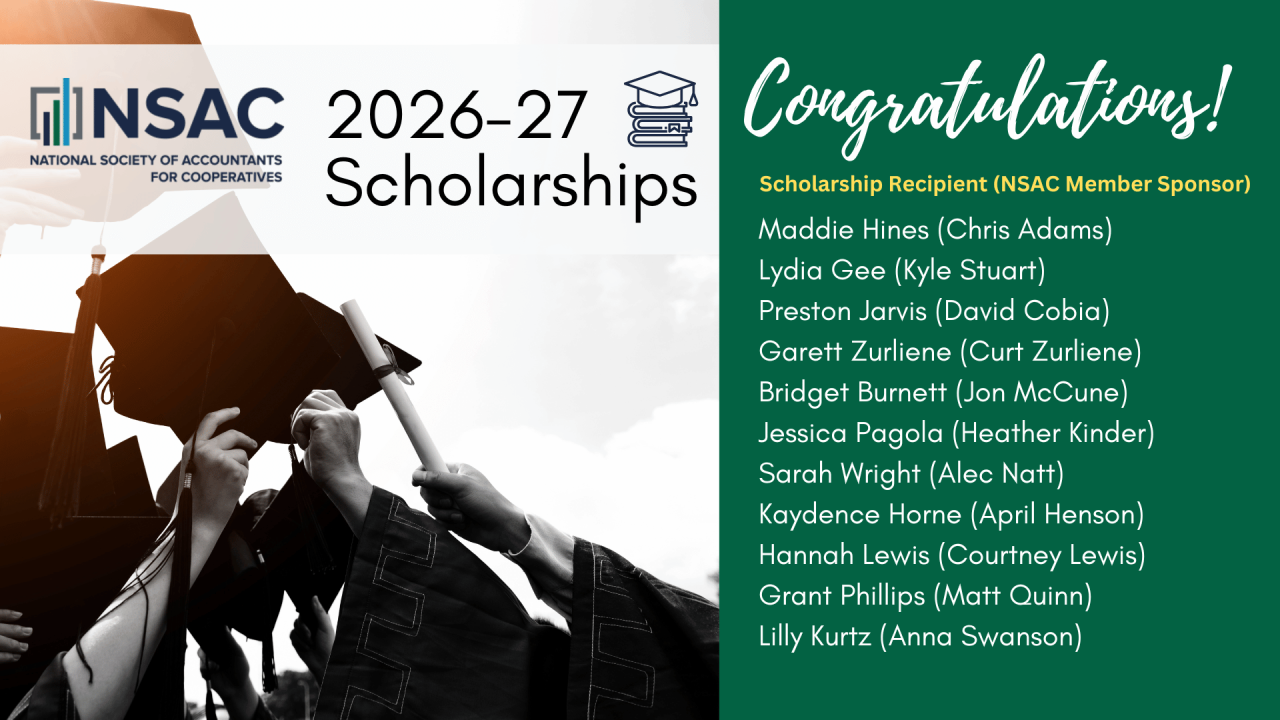
NSAC Announces 2026–2027 Scholarship Recipients
Investing in the next generation of leaders is one of the most meaningful ways NSAC supports the cooperative community. Through its annual Scholarship Program, the National Society of Accountants for Cooperatives is proud to help outstanding students pursue their educational goals while encouraging academic excellence, leadership, and lifelong learning. This year, NSAC received an impressive number of applications from exceptionally talented ...
Read More
FASB ISSUES Accounting Standards Update 2025-10 GOVERNMENT GRANTS (Topic 832) Accounting for Government Grants Received by Business Entities – December 2025
Summary Why Is the FASB Issuing This Accounting Standards Update? The FASB is issuing this Update to improve generally accepted accounting principles (GAAP) by establishing authoritative guidance on the accounting for government grants received by business entities. GAAP does not provide specific authoritative guidance about the recognition, measurement, and presentation of a grant received by a business entity from a government.
Read More
Beyond the Numbers: Depreciation Studies as Strategic Tools for Electric Cooperatives
Introduction: Depreciation as a Strategic Utility Function Within the electric utility industry, depreciation is often viewed narrowly as an accounting requirement—a routine financial calculation necessary to allocate the cost of utility plant over time. Yet for electric cooperatives operating in today’s rapidly evolving energy environment, depreciation studies have become far more than technical accounting exercises. They are ...
Read More