February 2018 Article Archives
The Cooperative Accountant Fall 2026
The Fall 2026 issue of The Cooperative Accountant (TCA) has been released! Focusing on cooperative-related issues, such as accounting and auditing, finance, cooperative management, legal and regulatory issues and taxation, this journal has become widely recognized as the industry standard. NSAC members, please log into Connect to view or download the latest issue.
Read More
NSAC Announces Nominations are Open for the 2027 Silver Bowl Award
We’re thrilled to share that nominations are now open for NSAC’s most prestigious honor! We invite you to nominate an outstanding professional for the 2027 Silver Bowl Award. Since its inception in 1960, the Silver Bowl has been bestowed by NSAC leaders upon individuals who have distinguished themselves through long-term contributions that significantly elevate the fields of accounting, tax, and finance within the cooperative ...
Read More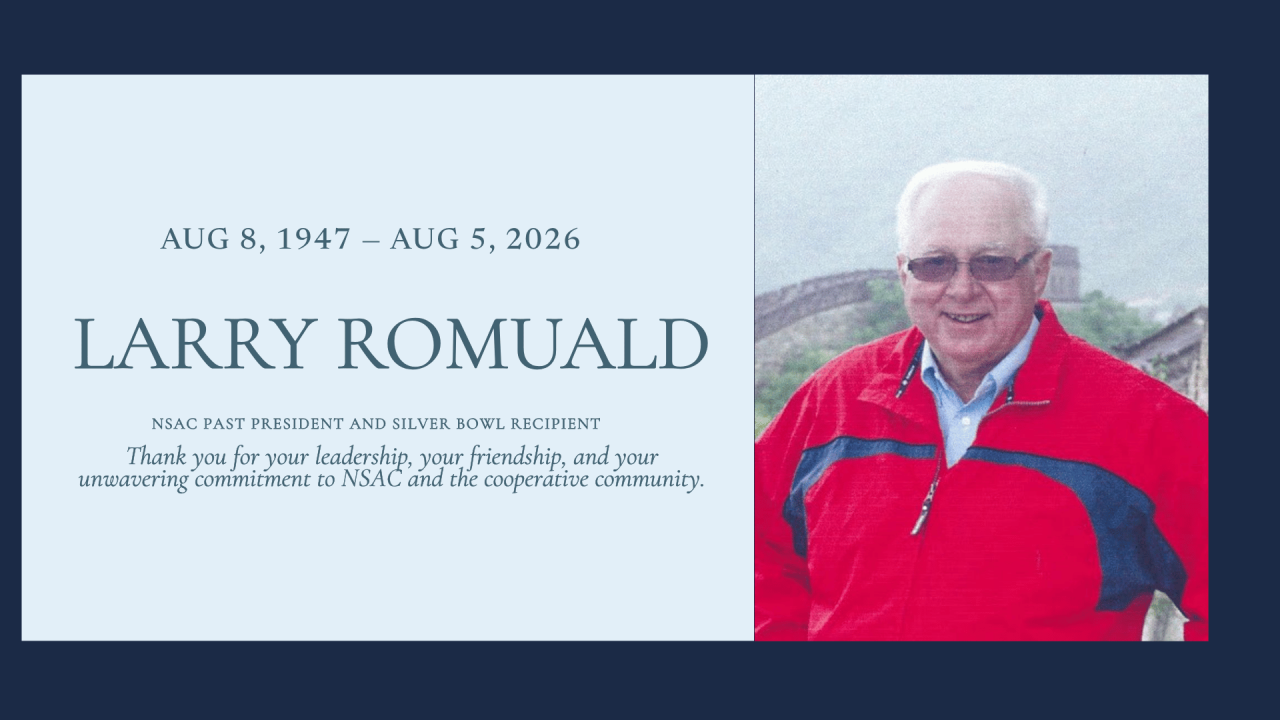
Honoring the Life and Legacy of Larry Romuald
It is with great sadness that we share the passing of Larry Romuald, a devoted leader, mentor, and friend to NSAC and so many throughout the cooperative community. Larry dedicated 42 years of his career to serving agricultural cooperatives, but those who knew him will remember him for far more than his professional accomplishments. He was a trusted advisor, a thoughtful leader, and someone who generously shared his knowledge and experience with ...
Read More
As Boomers Retire, Pressure Mounts to Expose Employee Stock Buyback Obligations
A retirement plan that runs on company stock can turn into a company’s next liquidity crisis — and U.S. accounting rule-setters are weighing whether businesses should be forced to spell out the size and timing of those buyback bills. The issue centers on employee stock ownership plans (ESOPs), a common way for private-company founders to sell their businesses to workers as they head for the exits. The pitch is easy to understand:
Read More
The Case Where the Chicken Comes Before the Egg
George v. Commissioner, T.C. Memo. 2026‑10 (Feb. 3, 2026) is one of the most consequential cases in the agriculture industry in recent years with respect to the research and development (R&D) credit under IRC §41. The U.S. Tax Court made it clear that agricultural innovation does not need a lab coat to qualify for the R&D credit. Production based experimentation, whether in barns, fields, or poultry houses, can count when aimed at ...
Read More